
Health insurance in Switzerland: the complete expat guide
Mandatory within three months, identical basic cover at every insurer, and premiums that vary by over CHF 200 a month between cantons. Everything you need to set up Swiss health insurance right in 2026 - with official BAG figures.
13 min read
Figures as of 2025/2026 - sources at the end of this article.
How the system works
Swiss basic health insurance is compulsory for every resident, sold by around 40 competing private insurers - but the benefits they sell are fixed by federal law and identical everywhere.
That combination is the single most important thing to understand. Because the benefit catalogue under the KVG/LAMal is set by law, an insurer cannot offer you a better basic policy - only a cheaper one. Acceptance is guaranteed, and premiums may not be priced on your health status, your income or your claims history. Insurers compete on price, service and administration, nothing else.
As a new arrival you have three months from registering at your commune to take out basic insurance. Do it inside that window and your cover starts retroactively on your arrival date - which also means the premiums are backdated, so waiting saves you nothing. If you miss the deadline, the cantonal authority can assign you an insurer, and a premium surcharge is possible (BAG, 2026 FAQ).
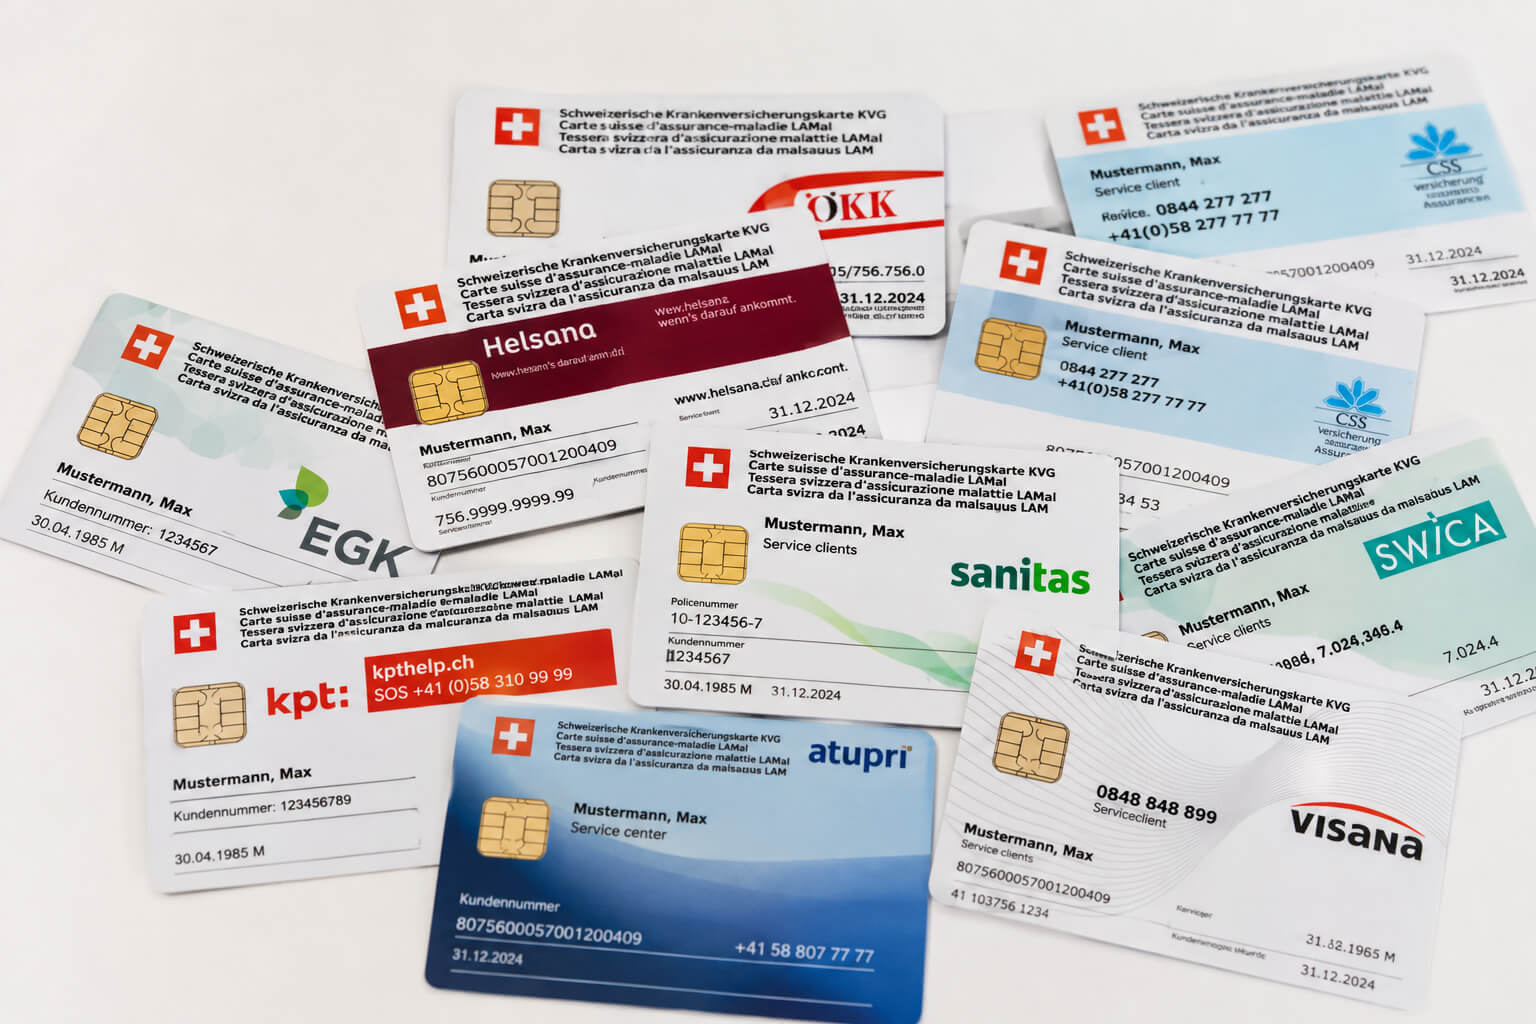
Practically: every family member needs their own policy, including newborns and children, and the household bill is the sum of individual premiums rather than a family rate. Read what basic insurance covers and work through our choosing health insurance checklist in your first weeks.
What it costs in 2026
The 2026 average premium across all insured people is CHF 393.30 a month, and where you live changes that figure by more than CHF 230.
| 2026 average premium | Per month | Note |
|---|---|---|
| All insured (mean) | CHF 393.30 | +4.4% on 2025 |
| Adults 26+ | CHF 465.30 | +4.1% |
| Young adults 19-25 | CHF 326.30 | Reduced tariff |
| Children (0-18) | CHF 122.50 | +4.9% |
| Ticino (highest canton) | CHF 501.50 | Cantonal mean |
| Geneva | CHF 489.80 | Cantonal mean |
| Appenzell Innerrhoden | CHF 270.70 | Cantonal mean |
| Zug (lowest canton) | CHF 264.50 | -14.7% |
All figures are official means for 2026 (BAG/priminfo). Adults aged 26 and over pay an average of CHF 465.30, young adults aged 19-25 benefit from a reduced tariff at CHF 326.30, and children average CHF 122.50 - which is why a family of four routinely budgets over CHF 1,100 a month.
Cantonal variation dwarfs almost every other saving available to you. Ticino at CHF 501.50 and Geneva at CHF 489.80 sit at the top; Zug at CHF 264.50 is the cheapest, helped by the canton temporarily covering 99% of inpatient costs, which pushed premiums there down 14.7%. Appenzell Innerrhoden follows at CHF 270.70.
2026 is the third consecutive year of increases, after roughly +6% in 2025 and +8.7% in 2024. Treat rising premiums as structural rather than exceptional, and build the annual comparison into your calendar rather than reacting to each announcement.
Franchise and cost-sharing
Your franchise is the annual amount you pay yourself before the insurer contributes, and choosing it well is the biggest lever inside a single policy.
Adults choose a franchise between CHF 300 and CHF 2,500; for children the range is CHF 0 to CHF 600. Once the franchise is used up you still pay a 10% retention on further treatment, capped at CHF 700 a year for adults and CHF 350 for children, plus a hospital contribution of CHF 15 per day of inpatient stay (BAG).
The maths is simple. A high franchise buys a lower premium, so a healthy adult who sees a doctor once or twice a year is usually better off at CHF 2,500. Someone with ongoing treatment, regular medication or a planned operation almost always wins with CHF 300, because they will hit the franchise regardless and the lower premium never compensates.
One reform to keep on your radar: parliament has moved to raise the minimum franchise to CHF 400 with automatic indexation to cost growth. It was still in consultation as of March 2026, the earliest realistic effect is around 2028, and children would be exempt (Federal Council). Our guide to choosing your franchise works through the break-even point for your own usage.
Care models: the easy discount
Agreeing a first point of contact for medical care cuts your premium by a double-digit percentage without changing a single legal benefit.
The standard model gives you free choice of doctor and is the most expensive. From there, three alternatives are common. A family doctor model - you always contact your GP first - typically saves around 10-20%. An HMO model, where you use a designated group practice, saves roughly 15-25%. A Telmed model, where you call a medical hotline before any consultation, saves roughly 15-20% (market-observed ranges, indicative).
In all of them the legal benefit catalogue is unchanged: you get the same treatments, the same medication and the same hospital cover. What you give up is the freedom to walk straight into any specialist's practice - and in emergencies, and usually for gynaecology and ophthalmology, even that restriction does not apply.
For most new arrivals a family doctor or Telmed model is the least painful saving available. Combined with a well-chosen franchise it routinely takes CHF 100 a month off an adult premium. See how basic insurance and its models work.
Switching and saving
Because basic benefits are identical by law, switching insurer is pure price arbitrage - and the deadline that matters is 30 November.
Your cancellation must reach the insurer by 30 November for a switch effective 1 January. "Reach", not "be postmarked" - send it early and keep proof. There is also a mid-year route: if you are on the standard model with the CHF 300 franchise, you can give notice by the end of March for a change on 30 June (ch.ch).
No insurer may refuse you basic insurance, and none may ask about your health for it, so there is no downside risk in switching. Never cancel the old policy before the new insurer has confirmed acceptance in writing, and never cancel while premiums are outstanding - unpaid premiums block a switch.
One benefit expats routinely miss: around 27% of residents receive cantonal premium reductions (Prämienverbilligung), worth an average of roughly CHF 2,080 a year (BAG statistics, indicative). Eligibility is income-based and set per canton, and in several cantons you have to apply rather than being assessed automatically. Check yours - families on a single income are often eligible without realising it.
Run the numbers with our premium comparison and follow the steps in switching insurer.
Supplemental insurance (VVG)
Supplemental cover is optional, sold under private contract law, and follows completely different rules from basic insurance.
Typical add-ons are semi-private or private hospital rooms and free choice of consultant, dental treatment, glasses and contact lenses, complementary medicine, and worldwide travel or emergency cover. These are the things the legal catalogue does not include or covers only partially.
The critical difference: unlike basic insurance, supplemental insurers may ask health questions, exclude pre-existing conditions or refuse you outright (BAG). Applications are underwritten. That makes timing a real factor - apply while you are healthy and young, because the same application after a diagnosis may come back with exclusions or a decline.
Keep basic and supplemental cover contractually separable, ideally at different insurers or at least as independent contracts. Otherwise the supplemental policy becomes an emotional anchor that stops you switching basic insurance freely - which is exactly where the annual savings are. Our supplemental insurance guide sets out which add-ons are worth their premium.
What's changing
The biggest structural reform in decades has already been voted through, and it starts to bite in 2028.
In November 2024 Swiss voters accepted EFAS, the uniform financing of health services. From 1 January 2028, ambulatory and inpatient care will be financed on the same key, with cantons contributing at least 26.9%; long-term care follows in 2032 (GDK). The intention is to remove the financial incentive that currently favours expensive inpatient treatment over cheaper outpatient care.
Alongside it sits the pending minimum-franchise reform described above - CHF 400 with automatic indexation, still in consultation as of March 2026, children exempt. Neither reform changes what you need to do this year, but both confirm the direction: more cost-sharing on the insured side, and continued pressure on premiums.
The practical takeaway has not changed in twenty years. Basic benefits are identical, so compare every autumn, choose the franchise and model that match your actual usage, check whether you qualify for a premium reduction, and buy supplemental cover while you are healthy. The rules keep moving; the discipline does not.
Common questions about Swiss health insurance
Is health insurance mandatory in Switzerland?
How much does Swiss health insurance cost in 2026?
Which canton has the cheapest premiums?
What franchise should I choose?
When can I switch insurer?
Is supplemental insurance worth it?
Sources
- BAG - health insurance premiums 2026 announcement
- priminfo.admin.ch - official premium database
- BAG - cost-sharing for persons resident in Switzerland
- BAG - FAQ on taking out insurance (2026)
- ch.ch - changing and cancelling health insurance
- Federal Council - consultation on the minimum franchise
- GDK - uniform financing of health services (EFAS)
- BAG - supplementary insurance
Figures marked indicative are estimates and are not formal insurance or tax advice.
Want your household premium checked?
30 minutes with an independent Hello Expats advisor - no obligation, no fees.